




Tom Hodgson and Ben Burton
Most families with substantial wealth already have the documents. They likely have a will, probably a trust, and powers of attorney in a folder somewhere. In practice, the documents are rarely a problem. The gap is in the details around them: which account passes to whom, how it is taxed once it lands, and whether the next generation knows what is coming.
An estimated $124 trillion is expected to move between generations over the next 20 to 25 years, with roughly $105 trillion going to heirs. Here is what matters most for high-net-worth families.
What is driving the Great Wealth Transfer?
Three forces are compounding at once. Household net worth in the U.S. has grown from roughly $20 trillion in 1990 to about $160 trillion today, a growth rate near 6% a year. Pensions have given way to 401(k)s and IRAs: a pension often ended with the retiree and spouse, while a retirement account leaves a balance behind. And people are living longer, with roughly a 50% chance that one spouse in a mid-60s couple reaches 90.
Why does inheriting later change the tax math?
Thirty-five years ago, the average age of someone receiving an inheritance was about 41. A decade ago, it was 51. Today it is closer to 60, squarely in peak earning years. Income above roughly $600,000 for a married couple is taxed at 37%, and the 3.8% net investment income tax applies to income above $250,000. A parent who deferred tax inside a 401(k) for 40 years may be handing a child a balance that comes out at a higher rate than the parent ever paid.
How is each asset taxed when it transfers?
Not all assets transfer the same way, and the differences drive the planning:
|
ASSET
|
WHO RECEIVED IT
|
TAX TREATMENT
|
|
Any asset
|
Surviving spouse
|
No immediate tax. An inherited IRA can be treated as the spouse’s own, with no 10-year clock.
|
|
Traditional IRA or 401(k)
|
Non-spouse heir
|
Emptied within 10 years; ordinary income at the heir’s rate.
|
|
Taxable accounts, real estate, business interests
|
Non-spouse heir
|
Full basis step-up at death; little or no gain if sold soon after.
|
|
Traditional IRA or 401(k)
|
Charity or donor-advised fund
|
No income tax on the distribution (the most efficient asset to give).
|
Timing matters between spouses too. Assets held in your name alone generally give your surviving spouse a full step-up in basis, while jointly titled assets typically receive a 50% increase. And a step-up does not end the story: an heir who inherits farmland or a business owes no immediate tax, then adds cash rent or operating income to their own bracket every year afterward.
How should heirs manage the 10-year window?
Current rules require heirs to empty an inherited account within 10 years. Depending on the decedent’s age at passing, this determines whether small annual required minimum distributions (RMDs) must be made. But that still leaves a large amount of control over timing:
- Defer distributions until after retirement, when a 37% bracket may become a ~20%-
range bracket.- Coordinate with a planned move. A distribution taken as a Florida resident avoids
the state tax a Nebraska resident owes, and Iowa now exempts IRA distributions
and pensions for retirees.
- Coordinate with a planned move. A distribution taken as a Florida resident avoids
- Offset withdrawals by increasing the beneficiary’s own 401(k) deferrals in the same
years (if not already maxing).- Spread the account across more beneficiaries. A $1 million IRA split among four
children fills four sets of lower brackets.
- Spread the account across more beneficiaries. A $1 million IRA split among four
Do you have enough tax diversification?
Where your assets sit matters as much as how much you have saved. Roth accounts are taxed going in and come out tax-free, including growth, and beneficiaries inherit that treatment. Traditional accounts give a deduction now and produce ordinary income later, for you or your heirs. Taxable accounts are taxed at capital gains rates and get a basis step-up at death.
The value shows up in retirement. You can draw from the pre-tax bucket to fill the lower brackets, then fund a large expense or a generational gift from the Roth or taxable bucket without pushing into a higher rate. However, for many earners who have accumulated most of their retirement savings in pre-tax accounts, the years before required minimum distributions begin can be an ideal time to take distributions or complete Roth conversions while they are still in lower tax brackets.
What happens to the accounts you have forgotten?
Roughly $1.7 trillion sits in lost or forgotten 401(k) accounts, with an average balance of nearly $56,000. Workers between 62 and 70 have changed jobs about a dozen times, and an employer plan cannot force out a balance above $7,000. A $7,000 account left behind at 30, compounding at 8% for 35 years, is worth roughly $100,000 at retirement, yet its beneficiary designation may not have been reviewed during that time. It points to a bigger problem. Beneficiary designations override a will, so a plan drafted last year can be undone by a form signed in 1998.
Estate Tax, Illiquid Assets, & Nebraska’s Inheritance Tax
The federal estate tax exclusion stands at $15 million in 2026, with a 40% rate above it. Recent legislation made that exclusion permanent, which means it is permanent until a future Congress decides otherwise.
For business owners and landowners, the real exposure is liquidity. If most of the estate is company stock or farmland, heirs may face a bill they can only pay by selling the asset you wanted them to keep. Fortunately, estate planning tools can help protect against that outcome, such as an irrevocable life insurance trust that can fund that estate tax liability outside the taxable estate.
Nebraska has no estate tax, but it does have a county-administered inheritance tax, and the rate depends on the beneficiary’s relationship to you.
|
BENEFICIARY
|
EXEMPTION
|
RATE
|
|
Surviving spouse
|
Fully exempt
|
0%
|
|
Children, parents, grandparents
|
$100,000
|
1%
|
|
More distant relatives
|
$40,000
|
11%
|
|
Unrelated individuals
|
$25,000
|
15%
|
It also reaches gifts made within three years of death. Nieces and nephews, a longtime employee, or an unmarried partner fall outside the favored categories: an 85-year-old widow leaving assets to a significant other is taxed as if leaving them to a stranger. In these cases, a well-thought-out lifetime gifting strategy can minimize those unintended consequences.
What happens if you do nothing?
Nebraska’s intestate laws decide, and the results surprise most people. If you have children from a living spouse, your spouse receives $100,000 plus half the remaining assets, and your children receive the other half. A will names your personal representative and guardians. A trust does more: it avoids probate when structured properly, adds privacy, and controls when a beneficiary receives assets rather than handing everything over at once.
Should you gift during your lifetime?
For many families, lifetime gifting accomplishes more than the estate plan does, and you get to see the result. In 2026, annual exclusion gifts run $19,000 per recipient, or $38,000 from a married couple, and gifting to a married child doubles that to $76,000 a year. Tuition and medical expenses paid directly to a school or provider do not count against the limit. Gifts above $19,000 require a gift tax return but rarely any tax; they simply reduce your $15 million exemption.
Which assets should go to charity?
If charity is part of your plan, the asset you choose matters more than the amount. Retirement accounts are the most tax-efficient gift to a charity, donor-advised fund, or foundation, because those organizations pay no income tax on the distribution. The same dollars left to a child are ordinary income. Name charities directly as IRA beneficiaries and leave the after-tax assets that receive a step-up to your family.
During your lifetime, three approaches do the most work.
- A qualified charitable distribution (QCD), available at 70½, sends money straight from an IRA to a charity, counts toward your required minimum distribution, and never enters your adjusted gross income.
- The 2026 QCD limit is $111,000 per person.
- Donating appreciated securities to a donor-advised fund avoids the capital gains tax a sale would trigger.
- Bunching several years of giving into one year can restore a deduction that smaller annual giving may no longer accomplish under higher standard deduction limits.
Have you talked with the next generation?
Retaining wealth is not only a matter of having the right documents. When a 60-year-old inherits a large traditional IRA with no warning, the first decision is often the expensive one. Heirs who know what may transfer, how it will be taxed, and who to call can plan around it. Every family draws its own line on what to share, but if your plan shows assets will be left over, that conversation is worth having while you can guide it.
Have you talked with the next generation?
Retaining wealth is not only a matter of having the right documents. When a 60-year-old inherits a large traditional IRA with no warning, the first decision is often the expensive one. Heirs who know what may transfer, how it will be taxed, and who to call can plan around it. Every family draws its own line on what to share, but if your plan shows assets will be left over, that conversation is worth having while you can guide it.
What steps should I take now?
- Build or refresh a plan that separates what you will need from what will become legacy assets.
- Review your estate documents every three to five years, and after any major life event.
- Confirm every beneficiary designation, including old employer plans and life insurance.
- Revisit your powers of attorney, healthcare directives, and trustee and executor appointments.
- Confirm with your advisors that what you have still matches current law and your intentions.
Plan for Your Family’s Future with Lutz
Families that navigate this well treat estate planning as ongoing coordination among their documents, titling, tax picture, and heirs. Our Lutz experts can help you evaluate wealth transfer strategies, model the tax impact of inherited assets, and prepare the next generation. Learn more about our tax and financial planning services, or contact us with questions about your situation.
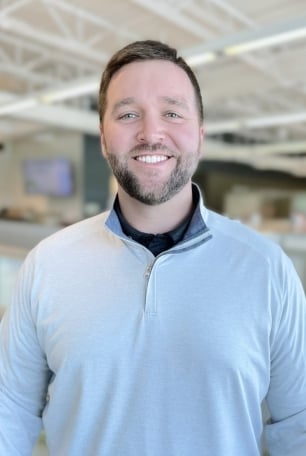
- Maximizer, Analytical, Futuristic, Relator, Strategic
Tom Hodgson, CFP®
Investment Advisor
Tom Hodgson, Investment Advisor, began his career in 2011. He has built extensive expertise in financial planning and wealth management while taking on leadership roles in training and estate planning initiatives.
Specializing in comprehensive financial planning and wealth management, Tom helps individuals and families navigate everything from retirement planning and investment management to education funding, estate planning, and tax-efficient strategies. He works closely with clients to develop personalized financial plans that evolve alongside their goals, providing practical guidance and ongoing support through every stage of life.
At Lutz, Tom is known for helping clients connect today’s decisions with what they want life to look like years from now. He takes a thoughtful, forward-looking approach to financial planning, simplifying complex decisions and adapting strategies as circumstances change. Clients appreciate his ability to listen first, anticipate needs, and provide steady guidance through important life and financial transitions. His genuine interest in understanding what matters most to each client has made him a valued advisor to individuals and families.
Tom lives in Elkhorn, NE, with his wife Carlie, their children Aubrey and Jack, and their dog Oakley. Outside the office, he can be found following the Jays and Huskers, cooking, golfing, and enjoying outdoor activities including hunting and fishing.
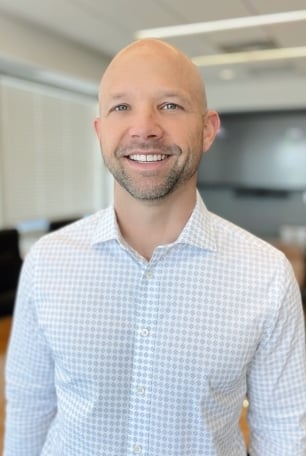
- Competition, Achiever, Relator, Focus, Arranger
Ben Burton
Tax Shareholder
Ben Burton, Tax Shareholder, began his career in 2006. Growing with Lutz since 2008, he has developed deep expertise in estate and gift tax planning while becoming a cornerstone of the firm's culture.
Specializing in tax consulting for closely held businesses and high-net-worth individuals, Ben focuses on creating comprehensive tax and wealth transfer strategies. He combines technical expertise with relationship-building skills to develop tailored solutions for complex tax scenarios. Ben values the opportunity to solve problems alongside clients and colleagues, taking a collaborative approach.
At Lutz, Ben makes the complex simple through his natural talent for arranging intricate tax planning solutions into clear, understandable terms. His ability to see how all the pieces fit together while explaining technical concepts in accessible terms has earned him leadership roles in the estate planning community, including serving as president of the Omaha Estate Planning Society.
Ben lives in Omaha, NE, with his wife, Kari Lou, and their five sons. Outside the office, he coordinates Lutz's Husker football tailgates, enjoys golfing and hunting, and cheering on his kids at their sporting events.
Recent News & Insights
Family Office
The Great Wealth Transfer: Retaining the Next Generation
Most families with substantial wealth already have the documents. They likely have a will, ...
Recent News
Lutz adds Phothisane and Rolf
Lutz, a Nebraska-based business solutions firm, recently added Sackey Phothisane and MaKayla ...
Client Advisory Services
Everything You Need to Know About Form W-4 and Form W-4N
Accurate tax withholding is a critical component of payroll compliance for businesses. While ...
Human Resources
What Employees Want in a Benefits Package & How to Deliver It
Finding and keeping great employees continues to be a challenge for many employers. Where ...
Let’s get you where you want to go.
We work to simplify complexities, help make critical business decisions, and confidently focus on the things that are truly important to you. We embrace your business as our own to spark the right solutions and help you thrive.